Market overview of the Rocket Propulsion Systems (Defense) Market
Our analysis indicates that the Rocket Propulsion Systems (Defense) Market encompasses advanced tactical missile motors, strategic booster stages, and associated guidance architectures. Operating under strict defense export controls like ITAR, the industry centers on specialized energetic materials, carbon-composite airframes, and high-temperature thermal protection systems essential for modern deterrence strategies worldwide.
Key market drivers, restraints, challenges, and opportunities shaping the sector
The market is propelled by escalating geopolitical friction and hypersonic weapons development, though severe supply chain bottlenecks for ammonium perchlorate and titanium sponge act as key restraints. Industry players face rigorous environmental compliance hurdles regarding perchlorates, creating fertile ground for innovators pioneering green monopropellants and additive manufacturing.
Emerging trends and growth patterns in the Rocket Propulsion Systems (Defense) Market
Our research highlights a massive shift toward solid-liquid hybrid propulsion and dual-pulse rocket motors that offer throttlable in-flight engagement profiles. Defense primes are aggressively integrating model-based systems engineering to compress development cycles for time-sensitive tactical missile requirements across allied nations.
COVID-19 impact analysis and recovery trajectory
The pandemic disrupted Tier-2 and Tier-3 specialty chemical suppliers, causing severe shortages of hydroxyl-terminated polybutadiene (HTPB) binder. However, government-backed stimulus packages and multi-year defense appropriations accelerated the sector's recovery, pushing the Rocket Propulsion Systems (Defense) Market size to 5.50 Billion by 2026.
Competitive landscape and strategic market concentration
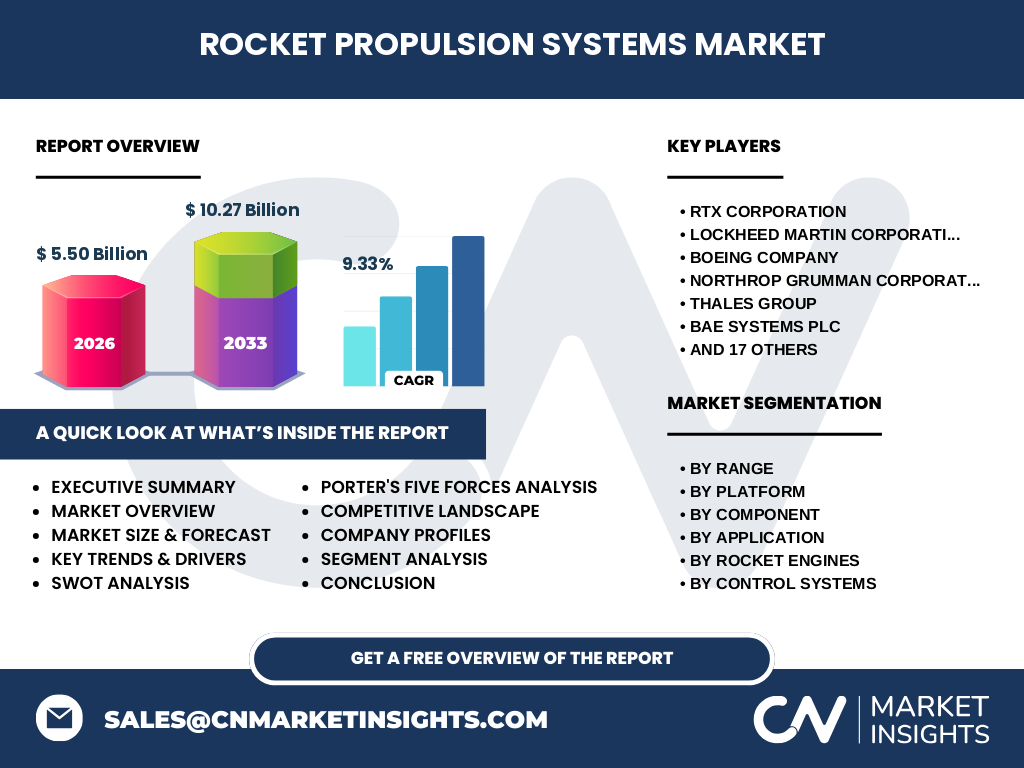
Market concentration remains high among defense primes like RTX Corporation, Lockheed Martin, and Northrop Grumman, who leverage vertical integration from energetic materials to complete guidance systems. Meanwhile, agile disruptors like Ursa Major and Spacefields capture niche opportunities through proprietary 3D-printed combustion chambers and novel solid propellants.
Executive summary of the Rocket Propulsion Systems (Defense) Market industry trends
Driven by rising defense budgets and technological modernization, the Rocket Propulsion Systems (Defense) Market is poised for stellar expansion. Based on our research, the market will surge from 5.50 Billion in 2026 to reach 10.27 Billion by 2033, registering a robust CAGR of 9.33%.
Market forecast from 2027 to 2033
Our predictive models indicate sustained upward momentum, with the Rocket Propulsion Systems (Defense) Market forecast projecting an expansion from 5.50 Billion in 2026 up to 10.27 Billion by 2033. This trajectory reflects an impressive 9.33% CAGR fueled by long-term procurement contracts for strategic deterrence.
Segmentation analysis across ranges, platforms, and components
The market breaks down by range into short, medium, intermediate, and long-range systems. Platforms span ground-based, airborne, naval, and space assets. Critical components comprise rocket engines, fuel and propellants, control systems, and structural elements like interstage structures and payload fairings, each fulfilling vital tactical roles.
Regional market analysis and geographic distribution performance
North America dominates global consumption due to massive Pentagon procurement programs involving prime contractors like Kratos and Boeing. Concurrently, the Asia-Pacific region exhibits the fastest growth velocity, propelled by escalating defense modernization initiatives across India, South Korea, and regional defense ecosystems.
In-depth regional review of key defense propulsion hotspots
European markets, supported by companies like Nammo and Avio, focus on sovereign missile stockpiles and green propulsion compliance under European Defence Agency guidelines. Meanwhile, the Middle East—anchored by firms such as Rafael and IAI—prioritizes advanced air-defense booster technologies and high-agility thrust vector control systems.
Strategic company positioning in the defense propulsion sector
Industry leaders optimize their positioning through targeted acquisitions and vertical integration. Major players like Northrop Grumman and RTX Corporation dominate solid rocket motor production, whereas specialized innovators like Karman Space & Defense focus on advanced thermal protection systems and high-temperature alloy structures.
Porter's Five Forces analysis of competitive intensity
Supplier power is remarkably high due to specialized requirements for aerospace-grade carbon fiber and energetic oxidizers. Threat of new entrants remains low, hindered by stringent government qualification standards, high capital expenditure for test fire stands, and deeply entrenched defense contractor relationships.
SWOT analysis of the Rocket Propulsion Systems (Defense) Market
Strengths include unmatched technological reliability and entrenched government ties. Weaknesses stem from long lead times for energetic raw materials. Opportunities lie in hypersonics and green propellants, while external threats involve strict environmental regulations and complex international defense export controls.
Value chain analysis from raw materials to end-users
The value chain initiates with upstream chemical refiners and carbon fiber manufacturers supplying raw inputs. Midstream participants fabricate solid grains, liquid fuel tanks, and guidance computers, culminating downstream with prime defense integrators delivering complete missile systems to military end-users.
Investment insights and high-potential areas
Investors should target companies developing green energetic formulations, advanced additive manufacturing for combustion chambers, and solid-liquid hybrid engines. These technological differentiators address regulatory pressures while offering superior throttle control crucial for modern tactical defense applications.
Conclusion and key takeaways for stakeholders
The Rocket Propulsion Systems (Defense) Market offers compelling growth, backed by a projected valuation of 10.27 Billion by 2033 at a 9.33% CAGR. Stakeholders must prioritize technological agility, supply chain resilience, and sustainable propulsion innovations to capture emerging defense contracts.
Research methodology for baseline triangulation
Our analytical framework triangulates data by cross-referencing military budget allocations from bodies like the US Department of Defense and European Defence Agency with primary qualitative interviews from propulsion engineers, trade registry data, and secondary macroeconomic indicators.
Scope of the report and coverage parameters
This report covers global defense propulsion systems across 2026 baseline data through 2033 forecasts, examining solid, liquid, hybrid, and cryogenic technologies. Limitations include restricted access to classified black-budget program specifics and proprietary nation-state defense inventories.
Recent developments in defense propulsion technology
Recent strategic moves feature major investments in solid rocket motor manufacturing capacity by primes like Northrop Grumman, alongside technological breakthroughs from innovators like Ursa Major in reusable liquid rocket engines and Green Propellant formulations by European suppliers.